435-590-0910
Get My Free Quote
Modern life insurance with living benefits can pay you if you're diagnosed with a critical or chronic illness — not just after you're gone. As an independent local agent in Southern Utah, we compare top carriers to find coverage that fits your health, family, and budget. No pressure. Just honest guidance.
*Sample term life rate for illustration. Actual premiums depend on age, health, coverage amount, term length, and underwriting, and are not guaranteed until a policy is issued.
Medicare & health carriers we're appointed with, including:
Life insurance carriers, including:
Pick the one that sounds most like you. We'll point you to the right place, and you can always call us if you're not sure.
Term life insurance, often with living benefits, for the years your family depends on you.
See term life →Coverage sized to your home loan, so your family can keep the house.
See mortgage protection →Compare Medicare Advantage, Medicare Supplement, and Part D options in Southern Utah.
See Medicare options →Simple, permanent coverage designed for funeral and end-of-life costs.
See final expense →Every conversation follows the same five steps, so you always know what comes next.
We start with your family, budget, and goals, not a product.
We explain your options in plain English.
We compare carriers and tell you if you don't need something.
You decide, on your timeline.
We're here for annual reviews and claims.
Many policies include living benefits (also called accelerated death benefit riders). They can let you access part of your death benefit if you face a qualifying illness. Here are the three common triggers:
If you're diagnosed with a covered condition, such as a heart attack, stroke, or invasive cancer, some policies let you take part of the death benefit as a lump sum.
If you can no longer do everyday activities such as bathing or dressing, or have a severe cognitive impairment, some policies let you access benefits to help pay for care.
If a physician certifies a limited life expectancy, many policies let you accelerate a large part of the death benefit.
Living benefits vary by carrier and policy, are not included in every policy, and may carry a charge. Using them reduces the death benefit your family would receive, and the amounts may be taxable or affect eligibility for public benefits.
Turning 65, or not sure your current plan still fits? We compare options from the carriers we represent, at no cost to you.
Plans that bundle hospital, medical, and often drug coverage, usually through a network.
Learn more →Also called Medigap. Works alongside Original Medicare to help with copays, coinsurance, and deductibles.
Learn more →October 15 to December 7 is your yearly window to review and change plans.
Plan your review →Marketplace, dental, vision, and short-term options for people under 65.
Learn more →Many modern policies include living benefits — so your coverage can help pay bills if you're diagnosed with a critical illness, chronic condition, or terminal illness, not only after you're gone.
Affordable protection for the years your family needs it most — now with living benefits that can pay you while you're still alive if you face a serious illness. Lock in a level monthly rate for the term and protect both your family and yourself.
Rates starting at $30/month* (sample; see note under the hero)
Learn More →
Lifetime coverage that never expires — and builds guaranteed cash value over time. A whole life policy is both protection and a long-term policy with guaranteed cash value.
Learn More →
Permanent life insurance with cash value linked to a market index (with a floor and a cap), plus living benefits that can help if you face a critical or chronic illness. Loans and withdrawals reduce the death benefit and can affect the policy.
Learn More →
Your home is your family's foundation. Protect it with coverage designed to pay off your mortgage if the unexpected happens — often with living benefits that can help keep the house if you become seriously ill.
Learn More →
Give your loved ones the gift of peace of mind. Final expense insurance covers funeral costs, medical bills, and end-of-life expenses — so your family isn't left with the burden during an already difficult time.
*Sample term life rate shown for illustration. Actual premiums depend on age, health, coverage amount, term length, and underwriting, and are not guaranteed until a policy is issued.
We're not locked into one insurance company. As a fully independent agency, we partner with multiple highly rated carriers — which means comparing options to find the plan that fits your life.
No call centers. No automated systems. You work directly with a licensed local agent who takes time to understand your situation and guides you through every step with zero pressure.
Quality protection doesn't have to break the bank. We find solutions that fit your budget without sacrificing the coverage your family actually needs — with some policies starting at less than a dollar a day for qualifying applicants.
Living benefits (also called accelerated death benefit riders) let you access part of your life insurance death benefit while you are alive if you are diagnosed with a qualifying critical, chronic, or terminal illness. They vary by carrier and policy, are not included in every policy, may carry a charge, and reduce the death benefit when used.
It depends on your income, debts such as a mortgage, how many people rely on you, and how long they would need support. Our free calculators can give you a planning estimate, and we're happy to walk through the numbers with you.
It depends on the carrier, the type of policy, your age, the amount of coverage, and your health. Some policies, such as many final expense plans, don't require an exam, while others do. We'll tell you what to expect before you apply.
No. Our consultations are free. Insurance carriers pay us a commission when you buy a policy or enroll in a plan, and your premium is the same whether you enroll directly or through an agent.
The main yearly window is Annual Enrollment, October 15 to December 7, with changes taking effect January 1. If you are turning 65, your Initial Enrollment Period is a separate seven-month window around your birthday. People already in a Medicare Advantage plan have another chance from January 1 to March 31, and special enrollment periods apply to certain life events.
Medicare Advantage (Part C) bundles your hospital, medical, and often drug coverage into one plan, usually through a network. Medicare Supplement (Medigap) works alongside Original Medicare to help cover costs such as copays, coinsurance, and deductibles. We'll help you compare how each could work for your situation.
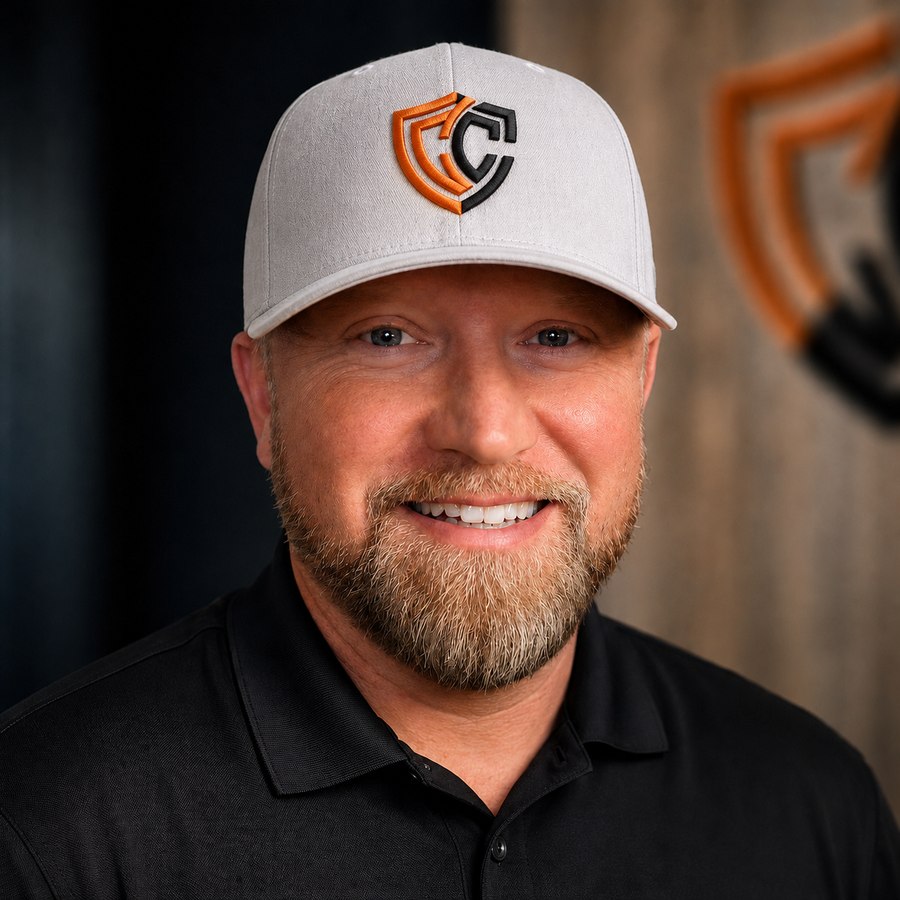
Hi, I'm Adam Walsh, a licensed independent insurance agent based in Cedar City, Utah. I help families across Southern Utah compare life insurance and Medicare options from multiple carriers, and I'll tell you plainly what I'd recommend and why. You work directly with me, not a call center.
Adam T. Walsh · Licensed Insurance Agent · UT License #1057754 · NPN #21425500
More about me →Talk it through with a licensed local agent, or request a callback. It's free, with no obligation and no pressure.